Commercial Insurance Appraisal
Commercial value breaks where templates stop
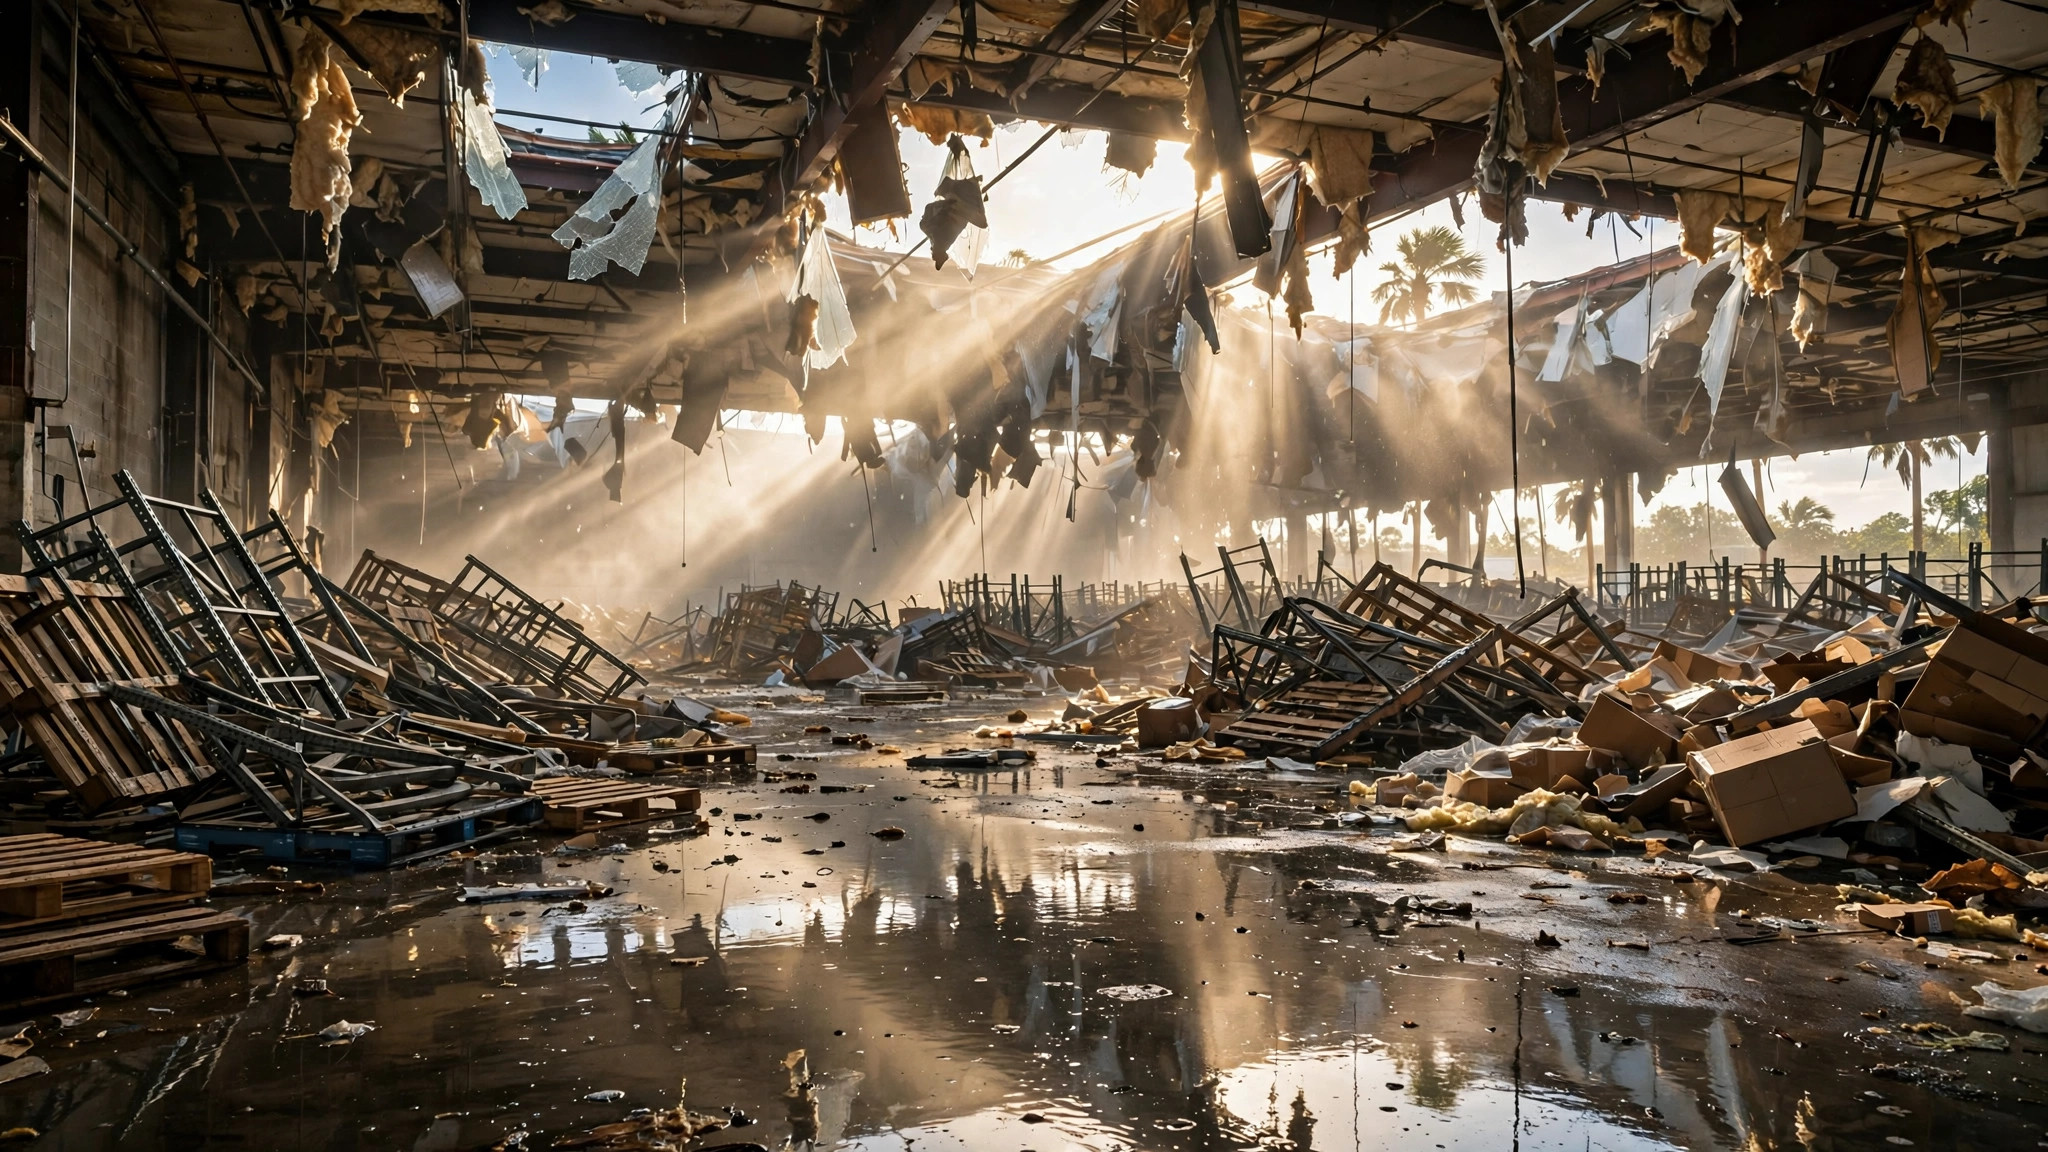
A commercial building is not priced by the square foot alone. A TPO roof with wet ISO board does not repair like a shingle roof. A tenant build-out does not price like shell space. Switchgear does not arrive on a painter's schedule. A code-triggered life safety repair does not disappear because a template has no line for it.
Loss Recovery Experts values the property as a working system. We document what was damaged, how it must be restored, what records control responsibility, and what the work costs.
The documents decide responsibility before price
Commercial responsibility can turn on more than the policy. The review may need:
- The complete policy, declarations, forms, and endorsements.
- Leases and work letters.
- Tenant improvement records.
- Association declarations and governing documents where applicable.
- Maintenance and repair agreements.
- Prior capital improvement records.
- Rent rolls, operating statements, and occupancy records.
- Plans, permits, inspections, and code correspondence.
The firm identifies the property interests relevant to the appraisal before assigning values. It does not assume that the owner, tenant, association, or another party owns every damaged item.
What the physical valuation must capture
Roof systems
TPO, PVC, modified bitumen, built-up, metal, tile, and shingle systems use different repair logic. The record should identify the membrane or covering, seams, fasteners, insulation, cover board, deck, flashing, drains, parapets, coping, and rooftop equipment. Wet ISO and other wet assembly materials matter because a dry surface price does not restore a saturated system.
Building envelope
Storefronts, curtain walls, joints, cladding, waterproofing, doors, and openings must work together. Water entry at one transition can damage finishes and systems far from the opening.
Electrical and life safety
Switchgear, panels, feeders, emergency power, alarms, sprinklers, exit systems, and communications can drive both cost and restoration time. Lead times for switchgear and specialty equipment belong in the schedule record when procurement affects the loss.
Tenant improvements and operations
Demising walls, kitchens, medical or office build-outs, refrigeration, signage, docks, and specialty installations must be priced as they existed, subject to the policy and lease record. Phasing, night work, tenant access, and temporary operations can also affect the repair method.
Code-triggered work
The estimate should tie each code item to the repair and the authority requiring it. It should separate damaged property, required related work, and voluntary upgrades.
Experts we may coordinate with
A commercial appraisal may require:
- Engineers.
- Roof consultants.
- Industrial hygienists.
- Forensic accountants.
- Building consultants.
- Code consultants.
- Specialty contractors.
- Equipment experts.
- Fire investigators.
- Meteorologists where relevant.
The loss determines the team. We do not add experts for show. We bring in specialized disciplines when the disputed valuation requires them.
One commercial result, on the record
One recorded commercial case increased 157 percent through appraisal. The final valuation was approximately 2.6× the insurer's first number. Dollar amounts were not released, and none are shown here.
We work with all major carriers
Experience With Claims Involving Major Property Insurers
Carrier logos identify insurers involved in property claims and do not imply affiliation or endorsement.
Who handles the appraisal
Nathan serves as the appraiser you select. His job is to approach the loss with an open mind, independently evaluate the amount of loss, and support the valuation with evidence, construction knowledge, documentation, and professional judgment.
Nathan Sheppard, CPIA, CPAU, OSHA, FL#P193861
He brings 17 years of property claim experience to commercial, residential, and large-loss appraisal.
Commercial properties
- Apartment complexes
- Condo associations
- Hotels
- Shopping centers
- Warehouses and industrial properties
- Storage facilities
- Business interruption
- Large losses
Start with the controlling records
Send the policy, insurer estimate, leases or governing documents that affect responsibility, plans, expert reports, and operating records. The review reads the paper before it prices the property.