Residential Insurance Appraisal
The payment looks small because the repair was priced small
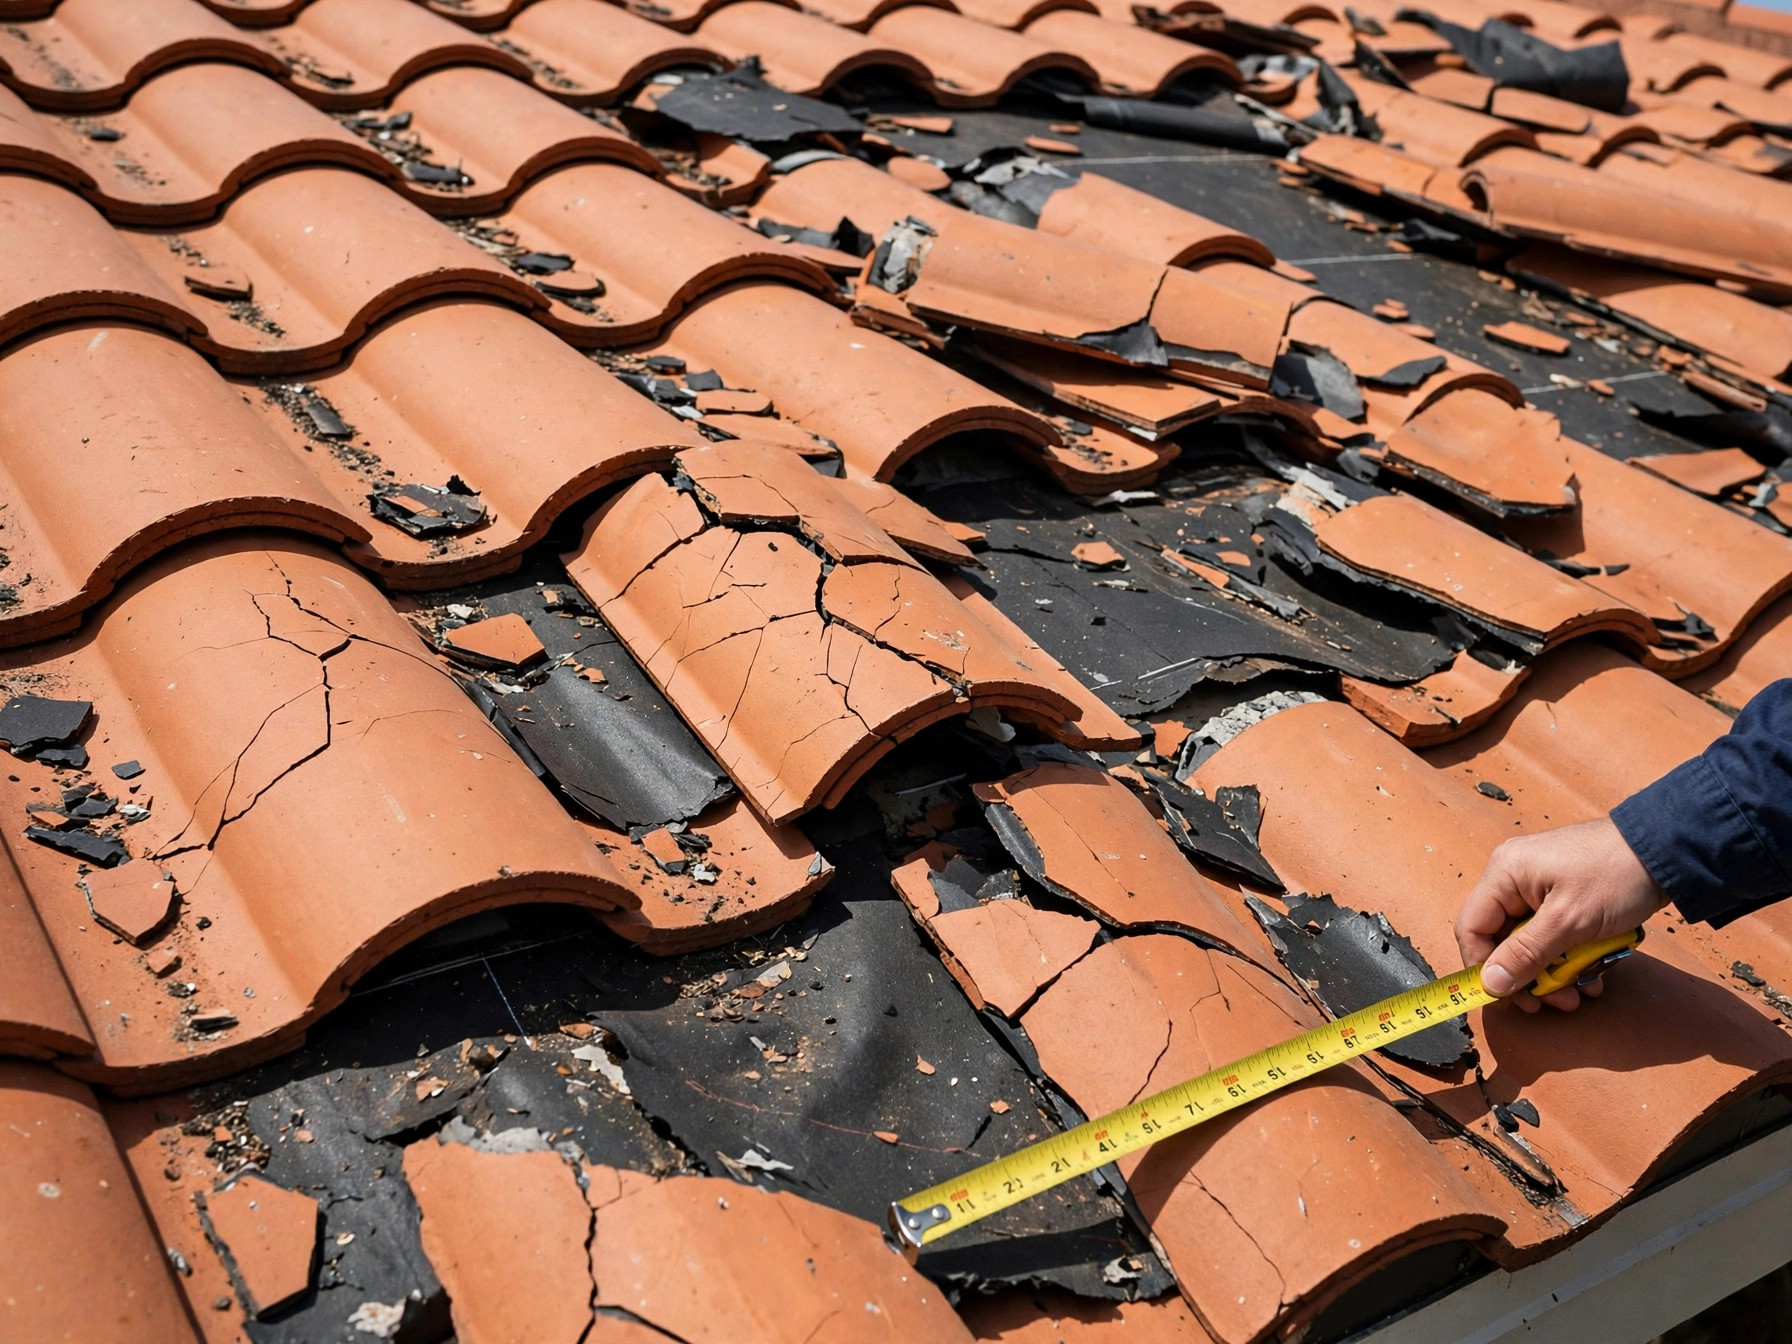
A residential estimate can miss the loss without missing the house. It may count the stained ceiling and not the wet material above it. It may price a few shingles and not the damaged roof field. It may replace a short run of flooring and ignore the access, matching, and continuity problems the repair creates.
Appraisal returns the dispute to the property. The panel needs the damaged assemblies, the repair method, the quantities, and the prices in one record.
Many property policies contain an appraisal provision. We start by reading yours.
How the appraisal works
You select an appraiser. The insurer selects an appraiser. Under a typical provision, the appraisers select an umpire and work toward a written award signed by two panel members. Your policy controls the process.
Nathan serves as the appraiser you select. His job is to approach the loss with an open mind, independently evaluate the amount of loss, and support the valuation with evidence, construction knowledge, documentation, and professional judgment.
What a complete home valuation examines
Roof assemblies
Shingle, tile, metal, and flat roof systems use different materials, fastening, flashing, and repair boundaries. The inspection documents the covering and the components affected below it. Slope, deck condition, penetrations, edges, and prior repairs all affect the method.
Water and moisture
Water travels along framing, insulation, ducts, and finishes. A visible stain is a clue, not a boundary. Moisture readings, selective openings where justified, photographs, and material conditions help define the affected area.
Access and detach and reset
Cabinetry, appliances, plumbing fixtures, electrical devices, doors, trim, and built-ins may need removal and reset to perform the repair. Drying, protection, storage, and reinstallation belong in the method when the work requires them.
Matching and continuity
Flooring, tile, cabinets, countertops, siding, paint, and roof materials may no longer match a small repair area. Check the actual policy for a matching exclusion or a conditioned matching endorsement before treating matching as settled. The physical record still needs to show where continuity breaks and what repair the property requires.
Interior systems
Electrical, plumbing, HVAC, insulation, drywall, and finishes work as connected systems. A wall repair can affect outlets, switches, duct runs, and adjacent rooms. The estimate should follow the repair through the system, not stop at the first visible surface.
Where first estimates often lose the thread
- Roof damage priced as isolated material replacement without the assembly.
- Moisture scope limited to the room where water became visible.
- Wet insulation or hidden material left untested.
- Detach and reset work omitted.
- Discontinued or continuous materials priced as simple spot repairs.
- Debris removal, permits, protection, and temporary repairs treated as afterthoughts.
- Depreciation applied without a clear item, age, condition, and useful-life record.
These are the items a complete valuation needs to address.
A recorded result
Mike's insurer's first number was $2,773.00. The appraisal award was $129,829.52. Difference: $127,056.52.
Approximately 46.8× the insurer's first number.
Past results do not predict another claim. The full results page labels the figures and their source limits.
Cost and role
A typical provision requires each party to pay its selected appraiser and share the umpire's expense. Your policy controls. Loss Recovery Experts bills by the hour. The total reflects the hours the assignment takes and cannot be known until the appraisal is complete.
Nathan does not serve as public adjuster and appraiser on the same claim.
Start with the estimate and the house
Send the policy, the insurer's estimate, payment letters, photographs, and any contractor estimate. The review compares the paper record with the repair the home actually needs.